
DLG Insights / Home insurance / 01
Condo Insurance: HOA Master Policy vs. HO‑6
You found the condo. Now check where the association’s insurance ends and your own policy needs to begin.
One address. Two policies to compare.
The homeowners or condominium association (HOA) is the organization that manages the condominium community. Its master policy is the association’s insurance contract. HO‑6 is a common name for an individual condo unit owner’s policy. Read both alongside the condominium documents: a wall, floor, fixture or upgrade cannot be assigned to a policy just by looking at it.
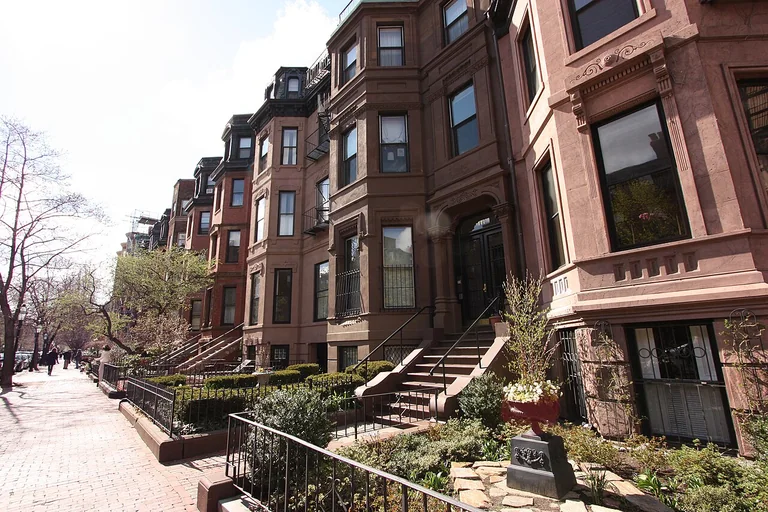

- Building exterior: Which parts of the roof and exterior does the master policy insure?
- Inside the unit: How are original finishes, cabinets and owner upgrades treated?
- Shared entries and stairs: What do the condo documents say about responsibility, deductibles and charges to owners after a loss?
Before you close: line up three documents
- Master policy information. Ask the association or manager for current coverage details, applicable endorsements and deductibles. If you receive a certificate or summary, ask for the policy details needed to resolve any gaps.
- Condo declaration and bylaws. Locate the unit boundaries, maintenance responsibilities and provisions that address master deductibles or loss assessments.
- A written unit policy quote. Ask a licensed insurance professional to compare the documents with the proposed coverage for interiors, improvements, belongings, personal liability and additional living expenses. Ask which losses could trigger loss assessment coverage, what limits or exclusions apply, and how the master deductible is treated.
Who does what? Your real estate agent can coordinate requests and deadlines. A licensed insurance professional reviews coverage and quotes. Your lender confirms its insurance requirements if you are financing.
A pipe leaks. Who pays?
Suppose water damages the hall and a renovated condo kitchen. Ask whether the cause of loss is covered, which policy addresses the shared hall and the unit’s finishes, and whether any part of the master deductible could be charged to owners. Ask how the unit policy would respond before assuming it would pay that charge.
- Trace the sourceWhat caused the water damage?
- Separate the damageShared hall, kitchen finishes, belongings.
- Verify the termsCoverage, deductibles, assessments.
Surface flooding is a separate question; ask whether you need separate coverage and see the DLG flood risk guide.
Start with who lives there
A policy form can help you start the conversation. Compare the actual terms and disclose how the property will be occupied.
- Owner-occupied house
- Ask about a homeowners form such as HO‑3.
- Condo owner
- Ask about HO‑6 and how it fits the association’s master policy.
- Tenant
- Ask about a renters form such as HO‑4 for personal property and liability.
- Landlord
- Ask about landlord or dwelling coverage, liability and loss of rental income after a covered event. Tell the insurer how the property will be rented.
Read the other guides in this series
Massachusetts & Virginia references
- Massachusetts Division of Insurance · Understanding Home Insurance
- Virginia SCC Bureau of Insurance · Virginia Homeowners Insurance Guide
For education. Policy wording, endorsements and association documents govern the coverage decision.